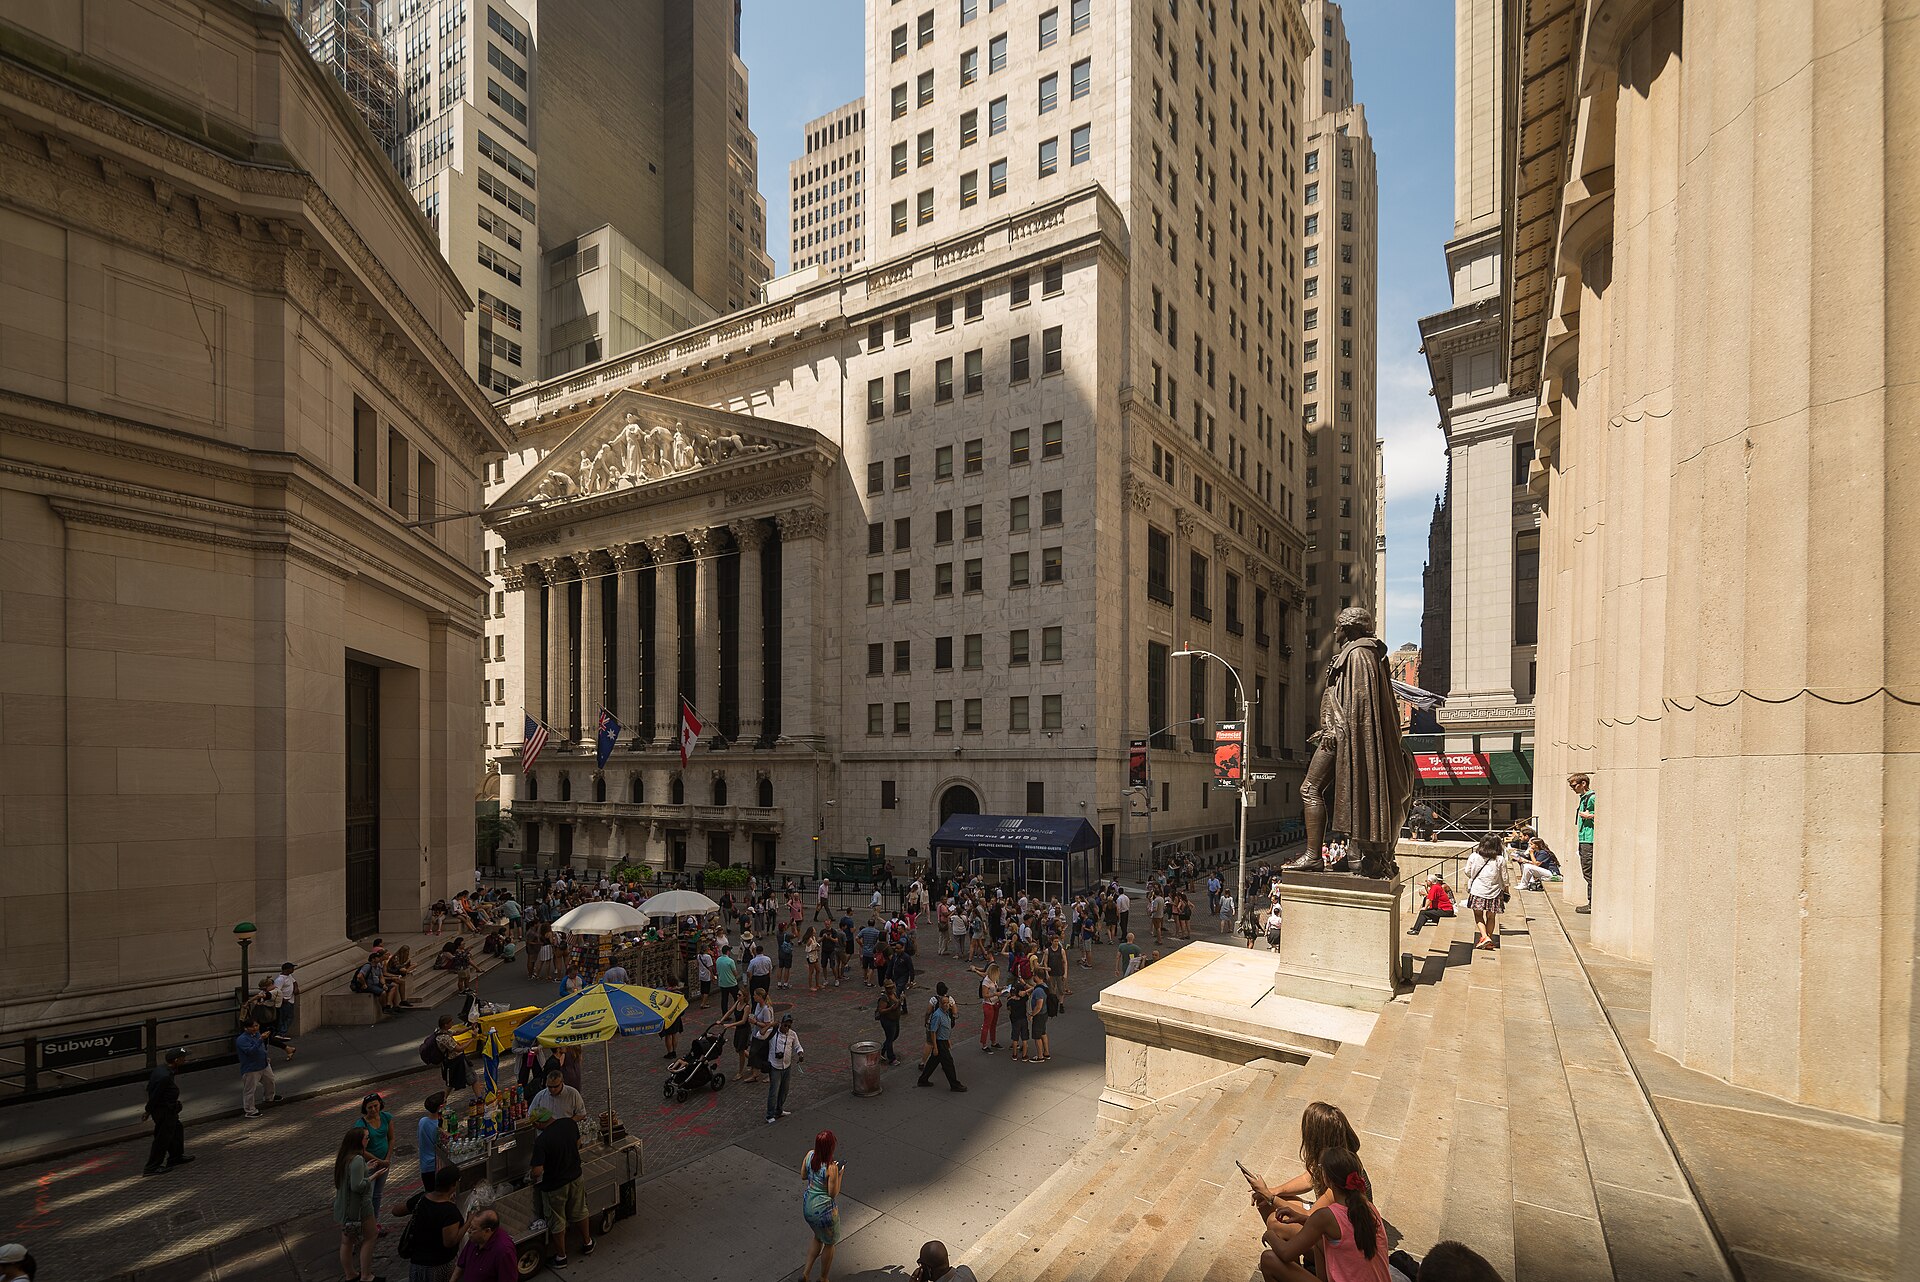
Wall Street endured its roughest session in months on Friday as disappointing results from Intel and Amazon reignited investor anxiety about the enormous sums pouring into artificial intelligence. The Dow Jones Industrial Average fell about 572 points, the S&P 500 dropped 1.8 percent, and the Nasdaq Composite plunged 2.84 percent, its steepest one-day fall since early June, capping a losing October for US equities.
Wall Street Earnings That Missed the Mood
Intel was the day’s casualty-in-chief, tumbling more than 25 percent after its outlook disappointed a market that had priced in a chip recovery. Amazon fell around 5 percent as investors recoiled at rising capital spending and softer guidance, following a similarly brutal reaction to Alphabet’s results a day earlier. Reddit lost roughly 30 percent on weak guidance, underlining how unforgiving the market has become toward any hint of slowing momentum.
The numbers behind the gloom tell a subtler story. According to LSEG data cited by Reuters, about 82 percent of the 299 S&P 500 companies that had reported third-quarter results beat expectations, and analysts still expect earnings growth above 30 percent. The selloff, in other words, is less about profits collapsing than about valuations that leave no room for disappointment.
The AI Spending Question
At the centre of the anxiety sits a simple question: when will the hundreds of billions spent on data centres and chips turn into revenue? Amazon, Alphabet, Microsoft and Meta spent more than $200 billion on capital investment in the third quarter alone. Bulls argue the build-out is a once-in-a-generation land grab; bears counter that depreciation charges will haunt earnings for years if demand disappoints.
The volatility also highlights how much index performance now depends on a handful of giants. As readers of our coverage of how central banks try to steady markets will know, policymakers watch episodes like this closely, because a disorderly repricing of technology shares can tighten financial conditions faster than any rate decision.
Defensives Find a Bid
Not everything fell. Energy shares were supported by strong results from Exxon Mobil and Chevron, healthcare names advanced after upbeat reports from Regeneron and AbbVie, and consumer staples such as Colgate-Palmolive climbed on raised guidance. Small-cap stocks also outperformed, suggesting rotation rather than panic: investors moved money toward cheaper, cash-generative companies instead of leaving the market entirely.
Attention now turns to Apple’s results after Monday’s close and a heavy week featuring AMD, Qualcomm and Palantir. For a fuller account of Friday’s numbers and the stocks that moved most, the day’s market report walks through the session in detail, including the trillion-dollar scale of the week’s losses in technology.
October ended the way much of it felt: profitable companies, nervous owners. The earnings season has shown an economy still generating strong profits, but a market increasingly unwilling to pay any price for growth. Whether November brings a recovery depends less on the next set of results than on whether investors decide the AI build-out deserves patience or a discount.